
Giants step back, ETF cools down: What is the real reason behind bitcoin's recent decline?

With structural support weakening, market volatility is expected to increase.
Original Author: Oluwapelumi Adejumo
Original Translation: Luffy, Foresight News
For most of 2025, Bitcoin's support level seemed unshakable because corporate digital asset treasuries (DAT) and exchange-traded funds (ETF) unexpectedly aligned, jointly forming a solid foundation of support.
Corporations purchased Bitcoin by issuing stocks and convertible bonds, while ETF inflows quietly absorbed the new supply. Together, these two forces built a robust demand base, helping Bitcoin withstand the pressures of a tightening financial environment.
Now, this foundation is beginning to loosen.
On November 3, Capriole Investments founder Charles Edwards posted on X that as institutional accumulation slowed, his bullish outlook had weakened.
He noted: "For the first time in 7 months, net institutional buying has fallen below the daily mining supply. This is not a good sign."
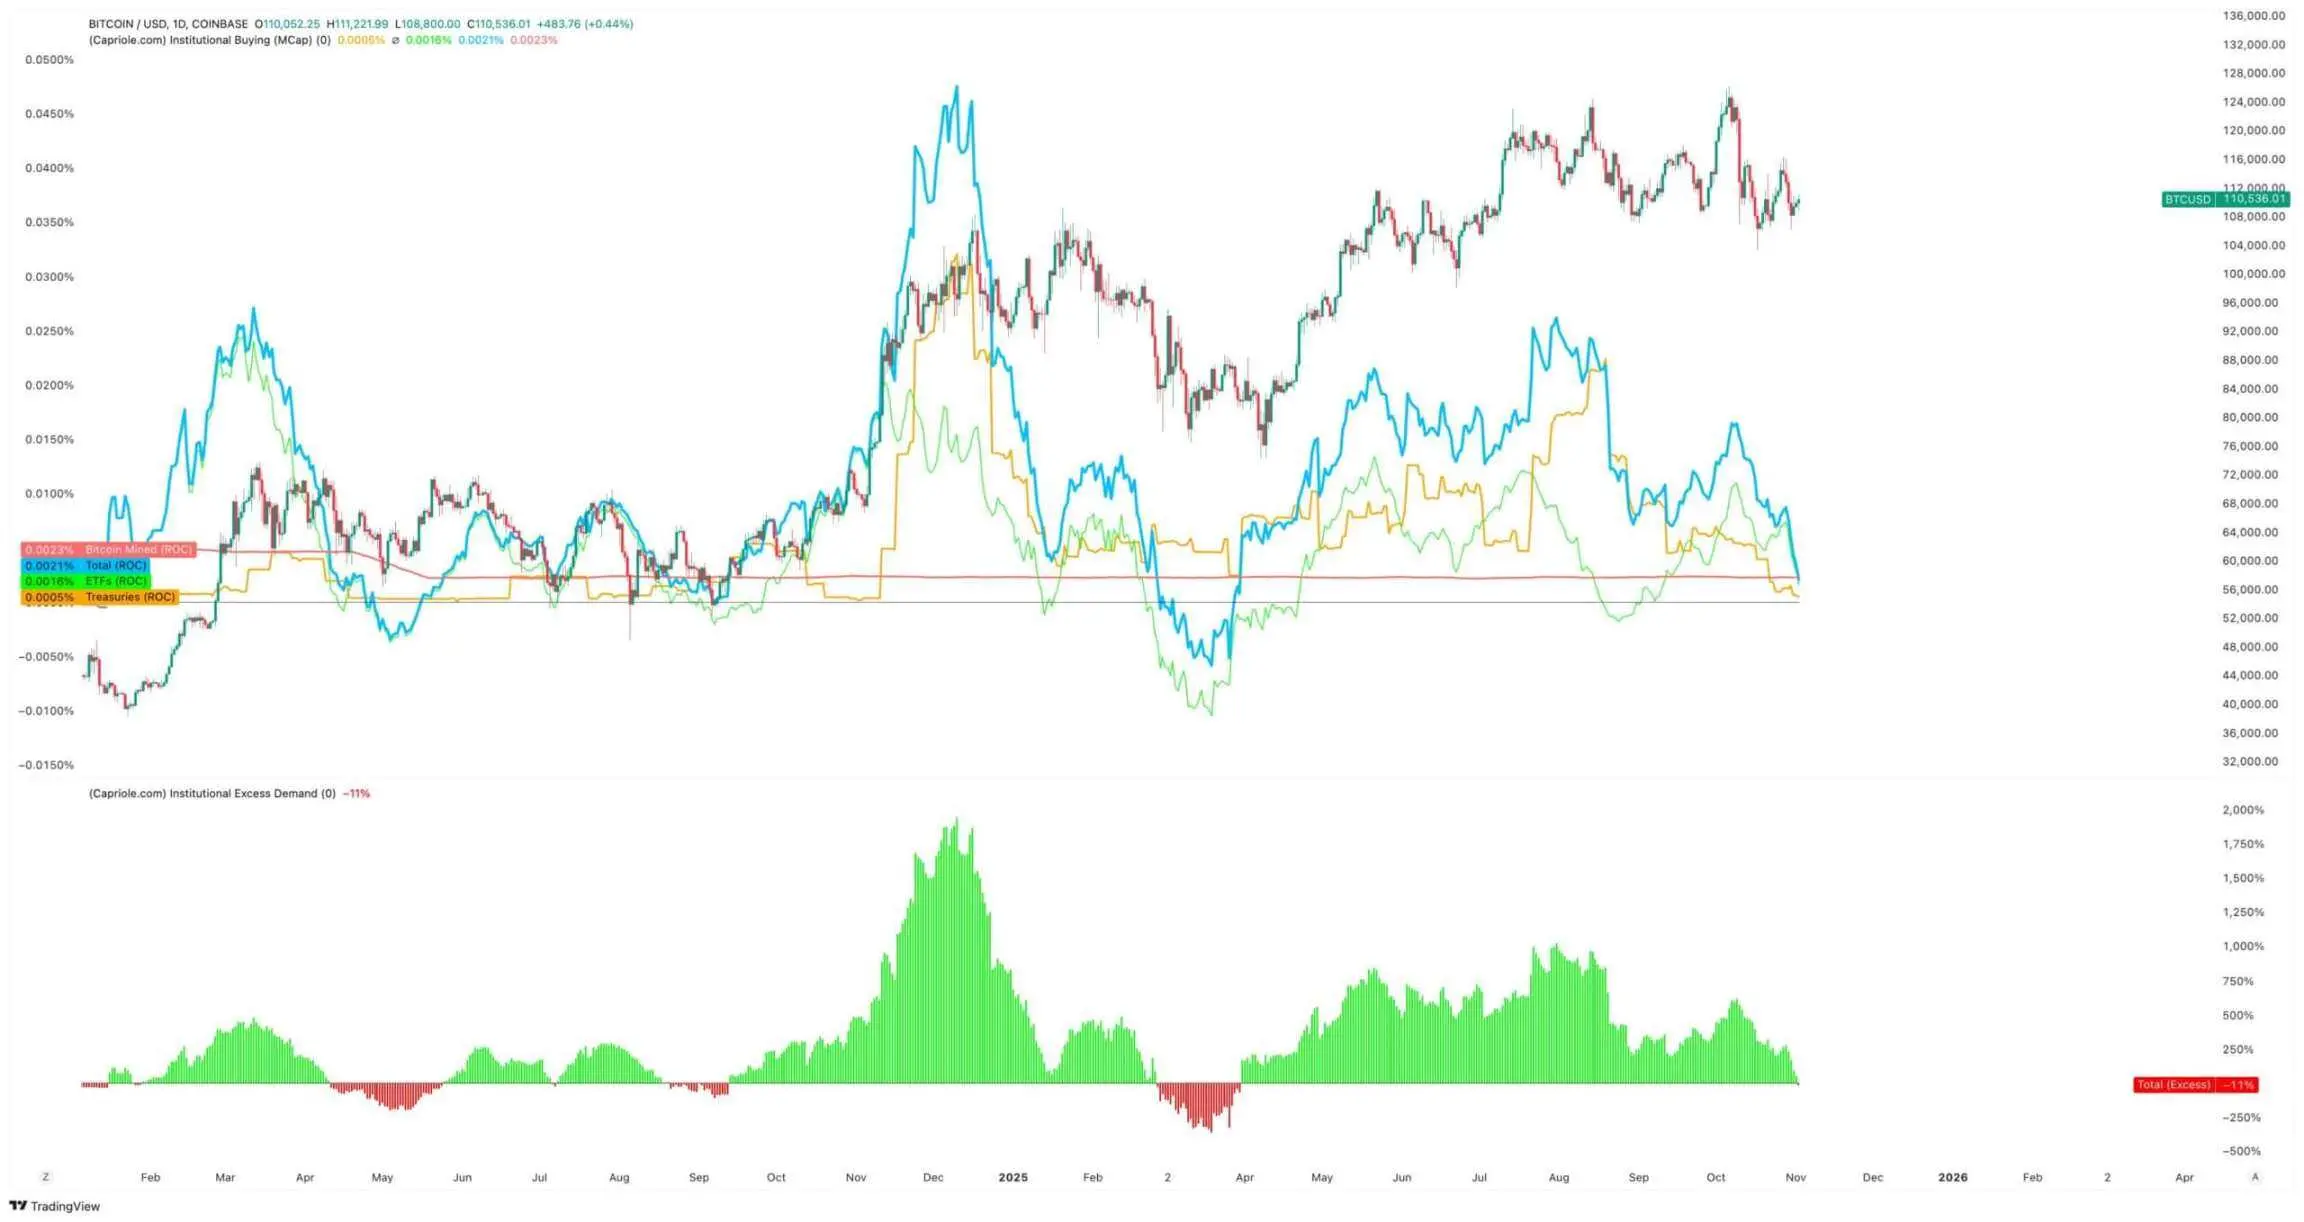
Bitcoin institutional buying volume, source: Capriole Investments
Edwards stated that even if other assets outperform Bitcoin, this indicator remains his key reason for optimism.
But as things stand, about 188 corporate treasuries hold significant Bitcoin positions, and many of these companies have relatively simple business models aside from their Bitcoin exposure.
Corporate Bitcoin Treasury Accumulation Slows
No company better represents corporate Bitcoin trading than the recently renamed "Strategy" (formerly MicroStrategy).
This software manufacturer, led by Michael Saylor, has transformed into a Bitcoin treasury company and currently holds over 674,000 Bitcoins, firmly maintaining its position as the world's largest single corporate holder.
However, its buying pace has slowed significantly in recent months.
Strategy added only about 43,000 Bitcoins in the third quarter, the lowest quarterly purchase this year. Considering that the company's Bitcoin purchases during this period sometimes dropped to just a few hundred coins, this figure is not surprising.
CryptoQuant analyst J.A. Maarturn explained that the slowdown in accumulation may be related to a decline in Strategy's net asset value (NAV).
He stated that investors once paid a high "NAV premium" for each $1 of Bitcoin on Strategy's balance sheet, essentially allowing shareholders to share in Bitcoin's upside through leveraged exposure. But since mid-year, this premium has narrowed sharply.
With the valuation premium diminished, issuing new shares to buy Bitcoin no longer brings significant added value, and the incentive for corporate financing and accumulation has also declined.
Maarturn pointed out: "Financing has become more difficult, and the stock issuance premium has dropped from 208% to 4%."
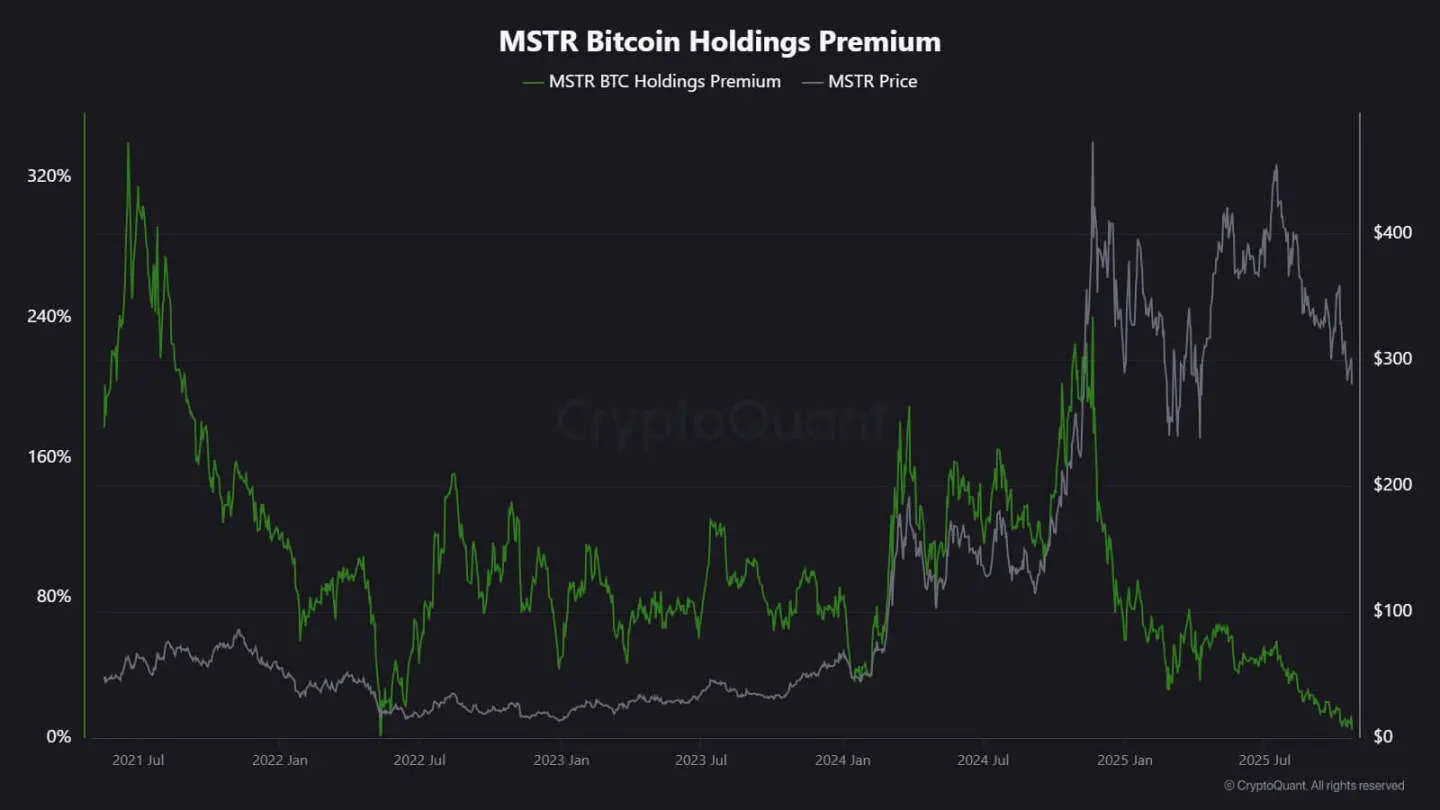
Strategy stock premium, source: CryptoQuant
Meanwhile, the cooling trend in accumulation is not limited to Strategy.
Tokyo-listed company Metaplanet once emulated this American pioneer, but after a sharp decline in its stock price, it recently traded below the market value of its Bitcoin holdings.
In response, the company approved a stock buyback plan and introduced new financing guidelines to expand its Bitcoin treasury. This move shows the company’s confidence in its balance sheet, but also highlights waning investor enthusiasm for the "crypto treasury" business model.
In fact, the slowdown in Bitcoin treasury accumulation has already led to some corporate mergers.
Last month, asset management firm Strive announced the acquisition of the smaller Bitcoin treasury company Semler Scientific. After the merger, these companies will hold nearly 11,000 Bitcoins.
These cases reflect structural constraints rather than a loss of conviction. When stock or convertible bond issuances can no longer command a market premium, inflows dry up and corporate accumulation naturally slows.
How Are ETF Flows?
The spot Bitcoin ETF, long regarded as an "automatic absorber of new supply," has also shown similar signs of weakness.
For most of 2025, these financial investment vehicles dominated net demand, with subscriptions consistently outpacing redemptions, especially as Bitcoin soared to all-time highs.
But by late October, their fund flows became unstable. Influenced by changing interest rate expectations, portfolio managers adjusted positions, risk departments cut exposure, and some weekly flows turned negative. This volatility marks a new behavioral phase for Bitcoin ETFs.
The macro environment has tightened, hopes for rapid rate cuts have faded, and liquidity conditions have cooled. Nevertheless, demand for Bitcoin exposure remains strong, but has shifted from "steady inflows" to "pulsed inflows."
Data from SoSoValue vividly reflects this shift. In the first two weeks of October, crypto asset investment products attracted nearly $6 billion in inflows; but by the end of the month, as redemptions rose to over $2 billion, part of the inflows was erased.
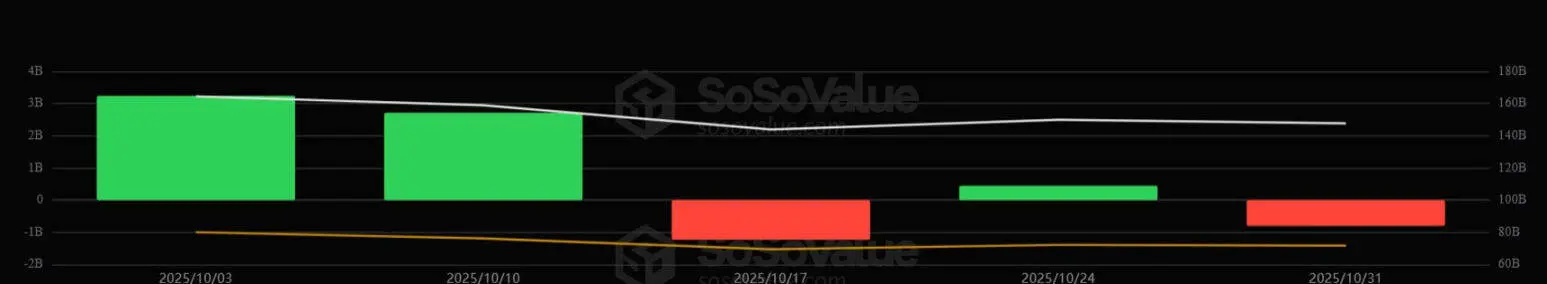
Bitcoin ETF weekly fund flows, source: SoSoValue
This pattern indicates that Bitcoin ETFs have matured into a true two-way market. They still provide deep liquidity and institutional access, but are no longer one-way accumulation tools.
When macro signals fluctuate, ETF investors may exit as quickly as they enter.
Market Impact on Bitcoin
This shift does not necessarily mean Bitcoin will decline, but it does signal increased volatility. As the absorption capacity of corporations and ETFs weakens, Bitcoin's price action will be increasingly driven by short-term traders and macro sentiment.
Edwards believes that in this scenario, new catalysts—such as monetary easing, regulatory clarity, or a return of risk appetite in the stock market—could reignite institutional buying.
But for now, marginal buyers are more cautious, making price discovery more sensitive to global liquidity cycles.
The impact is mainly reflected in two aspects:
First, the structural buying that once served as a support level is weakening. During periods of insufficient absorption, intraday volatility may intensify due to a lack of stable buyers to dampen swings. The April 2024 halving mechanically reduced new supply, but without sustained demand, scarcity alone cannot guarantee price appreciation.
Second, Bitcoin's correlation characteristics are changing. As balance sheet accumulation cools, the asset may once again fluctuate with the overall liquidity cycle. Periods of rising real interest rates and a strengthening dollar may pressure prices, while a loose environment could see Bitcoin regain its leadership during risk-on rallies.
Essentially, Bitcoin is re-entering a macro-reflexive phase, behaving more like a high-beta risk asset rather than digital gold.
Meanwhile, none of this negates Bitcoin's long-term narrative as a scarce, programmable asset. On the contrary, it reflects the growing influence of institutional dynamics—institutions that once shielded Bitcoin from retail-driven volatility are now the very mechanisms tying it more closely to capital markets.
The coming months will test whether Bitcoin can maintain its store-of-value properties in the absence of automatic corporate and ETF inflows.
If history is any guide, Bitcoin tends to be adaptive. When one demand channel slows, another emerges—perhaps from national reserves, fintech integration, or a return of retail investors during a macro easing cycle.
Original link
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Credit panic hits AI trading: CoreWeave bond yields remain high, Nasdaq posts biggest weekly drop since late June
Concerns over the debt risk of AI infrastructure companies continue to rise. Yields on some CoreWeave bonds briefly exceeded 15% on Thursday and remained elevated on Friday. CoreWeave's stock price plunged another 12% on Friday, and the Nasdaq Composite Index fell about 4.5% for the week. Analysts point out that as capital costs rise to unbearable levels, companies will have no choice but to reduce their capital expenditures.
Philadelphia Semiconductor Index Experiences Longest Losing Streak Since 2008; Jensen Huang Responds Calmly: Short-term Fluctuations Won't Change AI's Long-term Growth Prospects
Despite recent sell-offs in AI-related stocks, Nvidia CEO Jensen Huang remains confident in the long-term prospects of the AI industry.
U.S. chip stocks drop for eight consecutive sessions! $2 trillion wiped out in market value, marking the longest losing streak since 2008
This week, the investment prospects of AI were questioned by the market. The Philadelphia Semiconductor Index fell by 11.4%, and the Nasdaq dropped more than 4% in a single week. CoreWeave's stock price fell over 25% during the week, and its bonds dropped to distressed levels, casting doubt on the high-yield debt financing model. Strategists warned that being overly bearish could lead to missing opportunities, while "Wood Sister" bucked the trend and increased her holdings of CoreWeave.
In August, overseas funds returned to the U.S. Treasury market; UK holdings surpassed $1 trillion for the first time; Japan and China continued to reduce holdings, with China’s U.S. Treasury holdings hitting the lowest level since 2008
According to a report by the U.S. Treasury Department, overseas investors made net purchases of $108.9 billion in U.S. Treasury bonds in August, reversing a two-month decline in holdings. Among the top ten countries and regions holding U.S. debt, only China and Japan reduced their holdings in August. Japan, the largest holder, saw its holdings drop for the fourth consecutive month, reaching a 22-month low in the same month it intervened in the foreign exchange market. China’s holdings declined for the third straight month, hitting new lows for two consecutive months not seen since 2008. The UK, the second-largest holder, posted historic highs for two consecutive months. Canada recorded the largest increase in August, up $38.3 billion, ranking fifth overall. Belgium had the second-largest increase, up $19.8 billion.

Crypto prices
More


