Bitget App
Trade smarter
Buy cryptoMarketsTradeFuturesStocksEarnInstitutionAI & More
Raydium crypto surges 14% as negative funding raises short squeeze prospects

Raydium crypto surges 14% as negative funding raises short squeeze prospects

AMBCryptoAMBCrypto2026/10/08 21:33

Raydium [RAY] spent most of the summer going nowhere. Then in early September, it finally woke up.

Why does that matter today? Here’s the rundown.

Raydium crypto jumps 14% in a day!

Most of the market had a bad week, but Raydium clearly did not get the memo.

@media only screen and (min-width: 0px) and (min-height: 0px) { div[id^="bsa-zone_1774359638628-7_123456"] { min-height: 50px; transition: min-height 0.3s ease; } } @media only screen and (min-width: 640px) and (min-height: 0px) { div[id^="bsa-zone_1774359638628-7_123456"] { min-height: 90px; } }
AD

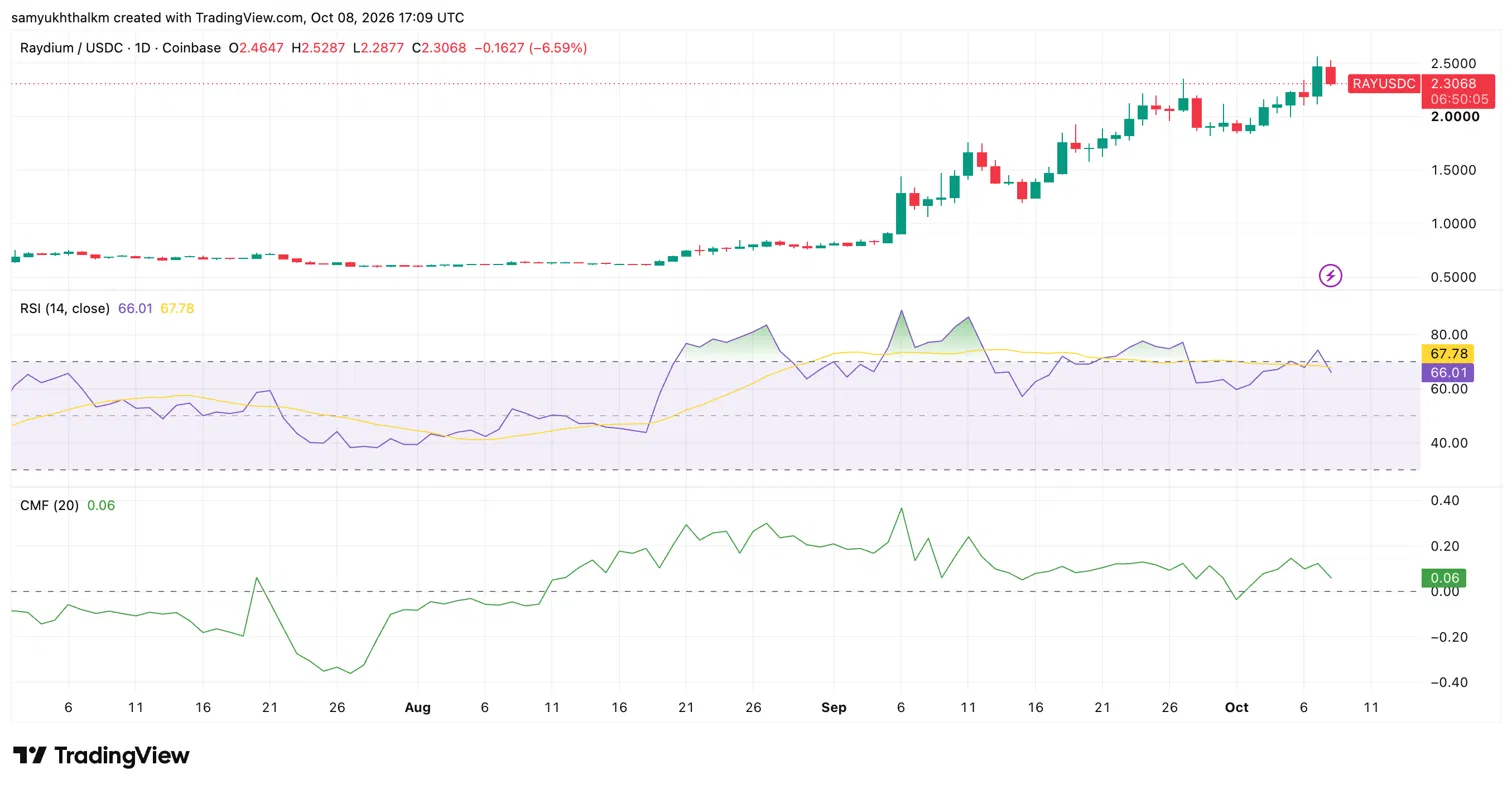
RAY traded around $0.90 before its September breakout and climbed as high as $2.56 on 7 October, an increase of roughly 184%. Even after retreating to $2.31, the token remained more than 150% above its early-September level.

That hardly makes a difference if you think of the bigger picture. Before its breakout on September 5, RAY was around $0.90.

It has more than doubled in the past month alone.

The pace is still there, but the tiredness is obvious. RSI was at 66; back in September, it was running above 80.

Chaikin Money Flow is positive at 0.06, but well off its September highs.

But here’s where it gets interesting.

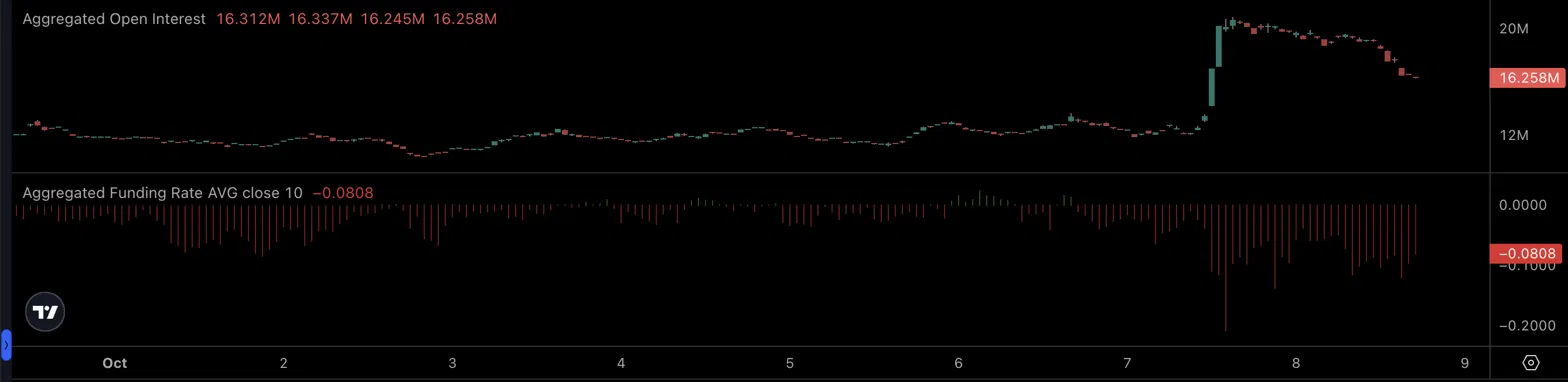
OI went from about $13 million to over $20 million during today’s rally. At the same time, funding went deep into the red, close to -0.20%.

A lot of traders opened short positions, betting the pump wouldn’t last. OI has since dropped to about $16.3 million, and funding is still negative at -0.08%.

The bears are still here, but in fewer numbers.

Why is RAY running when everything else isn’t?

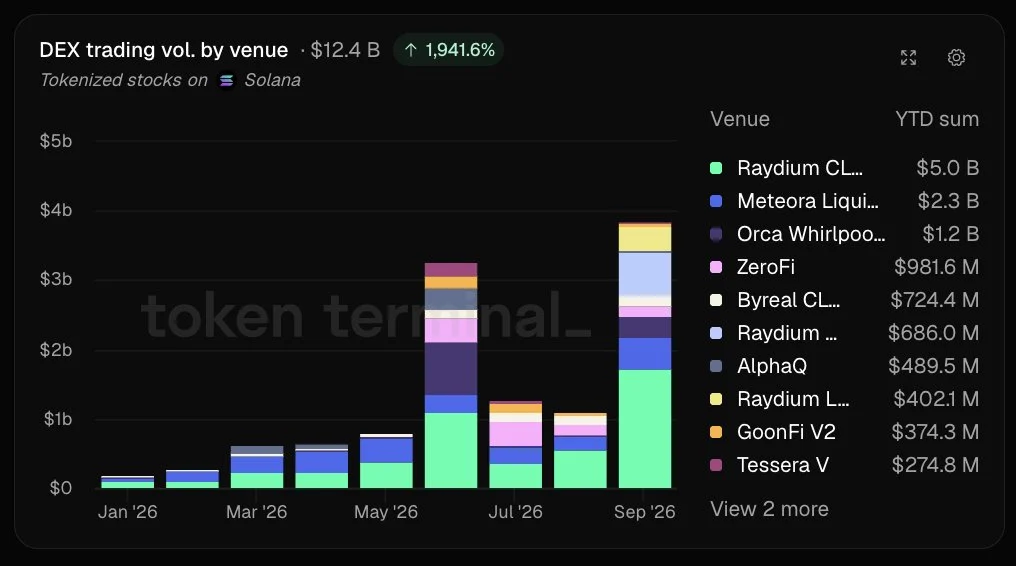
Meteora handled $2.3 billion, and Orca $1.2 billion. Those two together still don’t match Raydium.

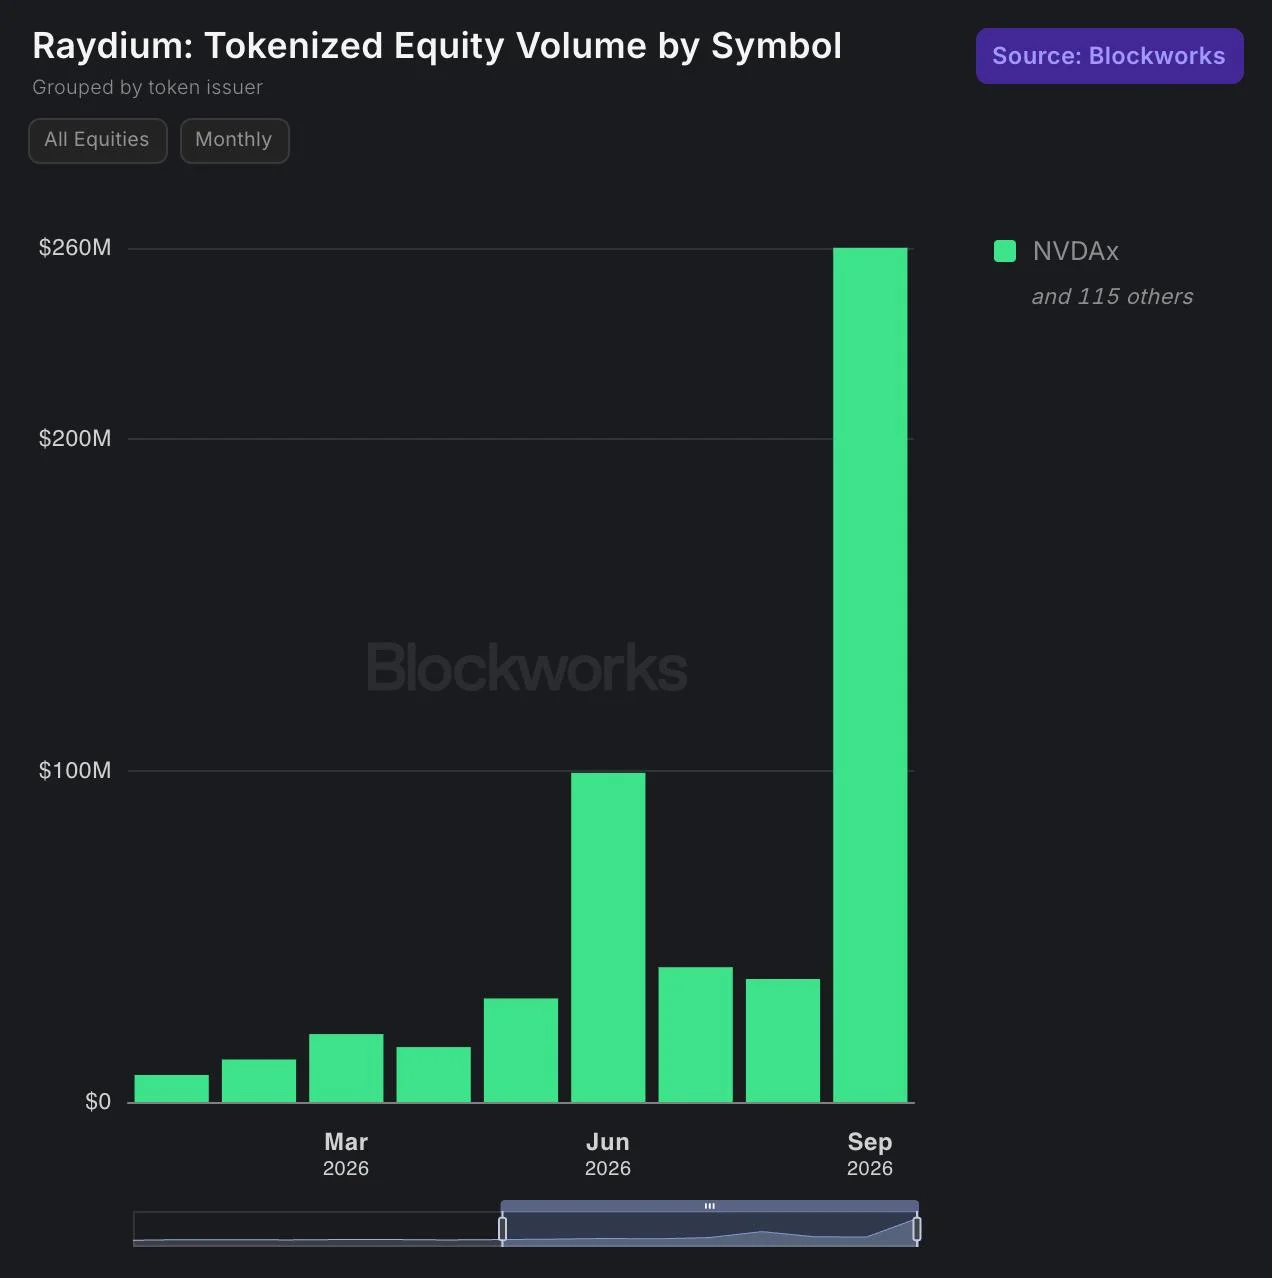
The most traded ticker? NVDAx, the tokenized version of NVIDIA. There were 115 others, but AI names were clearly what people came for.

So while most of the market sat this week out, RAY had actual trading volume behind it.

Final Summary

  • Raydium (RAY) jumped 14% in a day; more than doubled in the past month.
  • Raydium handled about $6.1 billion of Solana’s $12.4 billion tokenized stock DEX volume this year.
 

News Image 0News Image 1News Image 2News Image 3
0
0

Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.

Understand the market, then trade.
Bitget offers one-stop trading for cryptocurrencies, stocks, and gold.
Trade now!

You may also like

BUZZ - Brokerage opinion: Pepsi's growth strategy in the US still needs adjustment

October 9 - Snack and soft drink giant PepsiCo (PEP.O) warned on Thursday that the recovery of growth and profit margins in its key North American market will take longer than planned, and stated it will implement further cost-cutting measures to offset weak demand for its snacks and beverages. Twenty-five analysts have given the stock an average rating of "Hold," with a median target price of $145, according to data compiled by LSEG. JPMorgan (rating: "Neutral," target price: $137) pointed out that the company remains strong in international markets, but demand for snacks and beverages in North America remains weak, with limited signs of near-term improvement. Deutsche Bank (rating: "Hold," target price: $132) noted that PepsiCo's North American Beverages (PBNA) segment continues to lag the competition, with weak profit margins. Although the company plans to strengthen brand investment and execution, the path to sustained improvement remains unclear. Piper Sandler ("Overweight," target price: $140) indicated that the company faces weak U.S. demand and cost pressures. While new protein and hydration products may support growth, such prospects have yet to be validated. RBC Capital Markets ("Sector Perform," target price: $150) highlighted that North American beverages remain the main drag, while franchise re-authorization could support longer-term growth.

路透社•2026/10/09 10:00

Rothschild & Co Redburn Adjusts Price Target on Kimberly-Clark to $129 From $138

05:41 AM EDT, 10/09/2026 (MT Newswires) -- Kimberly-Clark (KMB) has an average rating of overweight and mean price target of $114.14, according to analysts polled by FactSet. (MT Newswires covers equity, commodity and economic research from major banks and research firms in North America, Asia and Europe. Research providers may contact us here: https://www.mtnewswires.com/contact-us)

MT newswire•2026/10/09 09:41

KWAP raises Inari stake to 385,836,100 shares (9.982%) after open-market purchase

KWAP raised its stake in Inari Amertron via an open-market purchase of 2,279,500 shares on Oct. 8. Total holdings increased to 385,836,100 shares, comprising 310,316,100 direct shares (8.03%) and 75,520,000 indirect shares (1.95%). The disclosure notice was dated Oct. 9. Disclaimer: This news brief was created by Public Technologies (PUBT) using generative artificial intelligence. While PUBT strives to provide accurate and timely information, this AI-generated content is for informational purposes only and should not be interpreted as financial, investment, or legal advice. Inari Amertron Bhd published the original content used to generate this news brief via Bursa Malaysia (KLSE) (Ref. ID: 3713681) on October 09, 2026, and is solely responsible for the information contained therein.

Bitget•2026/10/09 09:38

BUZZ - "Broker Views": Analysts skeptical about reports of Starbucks acquiring Chipotle

On October 9, the Financial Times reported Thursday that Starbucks SBUX.O had explored the potential acquisition of Chipotle CMG.N, a move that would see CEO Brian Niccol return to the Mexican burrito chain he once led. Starbucks declined to comment, stating the company would remain “fully focused” on its own business turnaround. **Limited Strategic Rationale** BTIG expressed “high skepticism,” noting that from a supply chain and operational perspective, the deal “does not make sense” and would cause significant dilution for Starbucks shareholders while disrupting management at both brands. BTIG analyst Peter Saleh stated: “Over the years, we've heard many stories about multi-brand acquisitions... but few actually happen, and even fewer succeed.” William Blair analyst Sharon Zackfia pointed out that, given the differences in supply chains, the deal offers “no clear revenue synergies and very limited benefits in procurement.” She also noted that as of June, Starbucks’ $9.4 billion net debt would make financing an acquisition “difficult to justify” and could raise the combined company's leverage ratio to about 6x, which is high in the publicly listed restaurant sector. D.A. Davidson indicated that given the distinct differences between the brands and limited apparent synergies, the likelihood of the deal succeeding is 20% or less. EMarketer analyst Suzy Davidkhanian commented that Niccol's familiarity with Chipotle could reduce execution risks, but Starbucks investors might view this transaction as a “costly distraction” hindering the company’s turnaround. (Note: For non-English speakers, Reuters provides automated translation of reports into several other languages for convenience. Due to potential errors and lack of required context, Reuters does not guarantee the accuracy of automated translations and assumes no liability for any damages or losses arising from their use.)

路透社•2026/10/09 09:36