
U.S. stocks are approaching historic highs, but institutions are deeply concerned! Goldman Sachs partner: Don't fight the market

As U.S. stocks approach historical highs, structural divergence within the market is reaching extreme levels, leading to heightened concerns among institutional investors.
Goldman Sachs partner Wilson maintains a bullish stance in his latest report, advising investors not to fight the market’s high concentration, and anticipates further room for stocks to rally before year-end. However, several strategists from within Goldman Sachs, as well as from Morgan Stanley and Bank of America, disagree, arguing that the macro environment is becoming tougher, the technology sector no longer enjoys strong tailwinds, and market risks are accumulating.
The core of this bull-bear divide lies in the fact that current U.S. equity earnings growth is highly reliant on a handful of stocks, market breadth is deteriorating, and volatility in the bond market and uncertainty around energy prices could become triggers for disruption at any moment.
Earnings Growth is Extremely Concentrated: Two Stocks Power One-Third of Gains
The concentration of earnings in the current U.S. stock cycle has reached its peak.
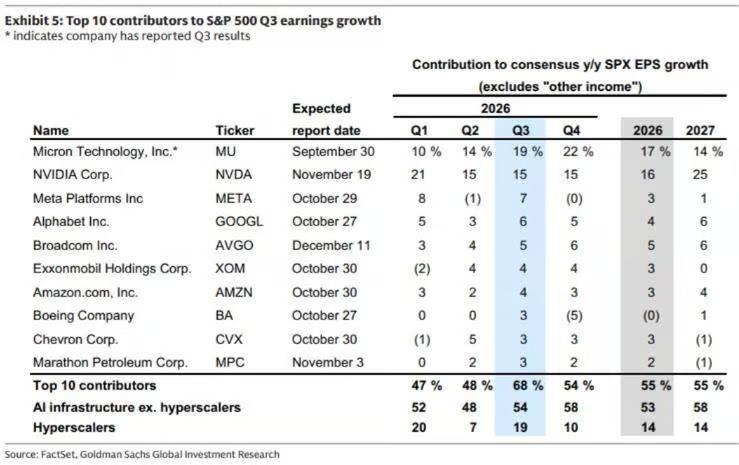
According to Goldman Sachs strategist Ben Snider’s "U.S. Weekly Kickstart: Q3 2026 Earnings Season Preview", S&P 500 earnings per share (EPS) growth is projected to reach 27% this quarter—a cycle high—before gradually slowing over the next three quarters.
What’s more notable is the extreme concentration of growth sources: This quarter, the top ten contributors will account for 68% of the S&P 500’s EPS growth, up from 48% in the prior quarter. Of this, just Micron Technology and Nvidia make up half of the 68%, contributing 19% and 15% of the total S&P 500 EPS growth, respectively. In other words, one memory chip manufacturer’s contribution to index earnings growth exceeds the combined total of Meta, Alphabet, and Amazon.
Meanwhile, median S&P 500 stocks have seen EPS growth slow from 14% to 9%, and margins have dropped from 15.1% to 14.7%. According to Snider’s data, at this current trend, by Q2 2027 overall market earnings growth will fall back to low single digits—at a time when the comparison base includes a quarter where tech giants booked about $150 billion in "other income" from revaluing equity investments, accounting for 12% of S&P 500 EPS.
Market Breadth Continues to Worsen; Most Stocks Deep in Correction
Despite indices being near record highs, internal market divergence is pronounced.
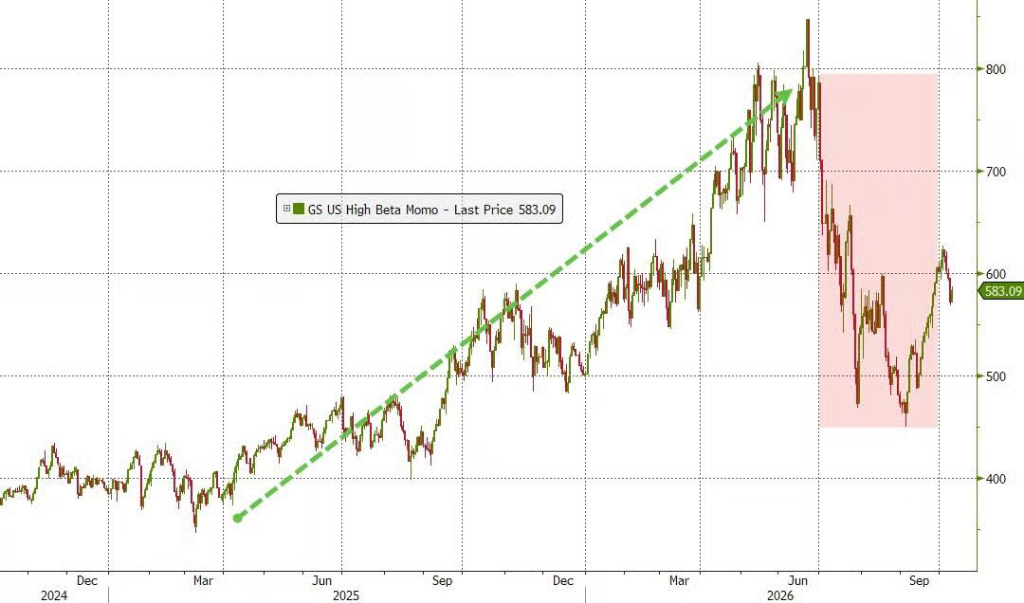
According to Nomura strategist Charlie McElligott, 85% of S&P 500 constituents have fallen more than 10% from their respective peaks, and 59% have fallen more than 20%. Goldman Sachs strategist Tuteja provides even starker numbers: Since August 27, the S&P 500 has gained a cumulative 1.3%, but excluding AI-related stocks, it has declined 5.2% over the same period.
This divergence is also present in European markets, though to a lesser extent. The top ten constituents of the STOXX Europe 600 account for about 17% of the index’s weight, while the top ten in the S&P 500 approach 40%. European market breadth is closer to its long-term historical average.
Divergence Among Institutions; Multiple Parties Warn of Downside Risk
Faced with these structural issues, institutional investors are not united in their outlook; clear divisions have even emerged within Goldman Sachs itself.
Goldman Sachs strategist Tuteja commented, "At current levels, I think the risk-reward for the tech/AI sector has shifted. The macro environment is clearly toughening, and positioning in AI and large-cap tech is no longer a tailwind." He cautions that if CPI data surpasses expectations and forces the Federal Reserve to resume rate hikes, all sectors will face short-term downside pressure.
Morgan Stanley strategist Mike Wilson previously warned that the S&P 500 could fall 10% to 7,100 points, and highlighted that the deterioration in market breadth "must be addressed in some way," with bond market volatility as the key variable.
Bank of America strategist Michael Hartnett revealed that in the week ending October 7, money market funds saw net inflows of $166.4 billion, the largest weekly inflow since April 2020. He summarized the precondition for funds to return to stocks in five words: "No rate cuts, no re-risking." Against the backdrop of the Federal Reserve remaining in a hiking cycle, this window may be delayed.
Nomura’s McElligott points out that the only visible fear in today’s options market is of right-tail risk (i.e., a major upside move)—S&P 500 call option skew is at the 99.6th percentile. However, he warns that if rates continue climbing alongside energy prices, the market could quickly switch to "growth scare" mode.
Goldman Sachs Partner Sticks to Bullish View but Preconditions Are Uncertain
In response to these doubts, Goldman Sachs partner Wilson maintains his bullish outlook and provides a detailed logical framework.
Wilson posits that as long as AI capital expenditure does not slow markedly, a sharp drop in rates should not be expected; however, if energy prices stabilize, bond market selling pressure will ease, paving the way for an equity rally into year-end. He urges investors "not to fight the high market concentration, which could become even more pronounced."
Wilson expects hyperscaler capex growth to peak this quarter, with consensus calling for 116% growth, while cloud computing backlogs are increasing even faster. He believes market leadership will gradually shift from the "pick-and-shovel" infrastructure suppliers to the largest AI spenders that are starting to show returns on their AI investments.
However, this bullish logic itself hinges on two major assumptions: First, continued expansion of AI capex means rates will stay high, which underlies Goldman’s optimistic view; second, the year-end rally depends on stable energy prices, but Brent crude has already reached $103, 63% of Gulf of Mexico capacity is offline due to hurricanes, and incidents like Iran attacking tankers near the Strait of Hormuz are escalating.
Market Structure Conceals Risks; Calm Hides Underlying Dangers
All things considered, the current U.S. stock market exhibits a fragile equilibrium.
Two stocks contribute a third of earnings growth, with growth peaking this quarter, and marginal buying is highly dependent on particular structural flows—this is less a coiled spring than a calm before the storm, where credit and rate market volatility have yet to fully transmit to equities.
However, as the article concludes: those bearish "phantoms" have been wrong all year long.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Micron now earns more than Apple! Apple urgently needs chips, Micron holds pricing power.
Micron Technology reported a net profit of $37.7 billion in the fourth fiscal quarter, surpassing Apple's $29.8 billion for the same period, thus becoming the more profitable company for the quarter. The memory shortage has given Micron strong pricing power, with its CEO stating that they “cannot meet customer demand.” The revenue guidance for next quarter is as high as $61.5 billion. Meanwhile, Apple's gross margin continues to be pressured by persistent memory costs, having dropped from 49.3% to a guidance range of 46.5%.
The "Eye of the Storm" in the Global Economy: Debt Crisis in Developed Countries
The IMF warns that developed economies are becoming the "eye of the storm" for global debt risks. Countries such as the United States and France accumulated high levels of debt during periods of low interest rates, but now rising interest rates are pushing up repayment costs, and fiscal consolidation faces political resistance. BofA Securities points out that the United States is facing declining tax revenues, France has structural income decline issues, and the UK and Japan are also under pressure. The deteriorating debt sustainability of developed countries may impact global financial markets through shocks in interest rates and capital flows.
The US market narrative undergoes a "dramatic reversal": shifting from "AI-driven deflation and controllable US debt" to "AI squeezing the bond market, and Bassen unable to control long-term interest rates"
Deutsche Bank points out that the market narrative regarding the U.S. economy has shifted from "AI drives down inflation" to "AI-related bond issuance pushes up U.S. Treasury yields," but pessimism may be overdone. The bank believes that the real risks underestimated by the market are security incidents in the AI ecosystem, failed IPOs, or underwhelming revenues, which could undermine the dollar and support the bond market. In addition, France's fiscal difficulties are putting new pressure on the euro.

Crypto prices
More


